
Lenme: Borrowing and Lending
- Rating
- 4.2
- Downloads
- 500.00K
- Content Rating
- Everyone
Lenme: Borrowing and Lending - Screenshots
Pros
- Quick access to peer-to-peer borrowing options
- Transparent loan requests help compare potential terms
- Useful alternative for people underserved by traditional banks
- Lenders can diversify funds across multiple loan requests
- Simple interface makes tracking active loans convenient
Cons
- Approval and funding are not guaranteed
- Interest rates and fees may vary between loan listings
- Late repayments can affect returns and create financial stress
- Availability and terms may depend on your location
- Requires careful review of borrower risk before lending
Lenme: Borrowing and Lending - Description
- App Name
- Lenme: Borrowing and Lending
- Package Name
- com.lenmoinc.lenmo
- Developer
- Lenme: Borrow and Lend
- Category
- Finance
- Last Updated
- Jan 10, 2019
- Version
- 26.6.1
When money is tight, the difficult part is often not finding a calculator or making a budget. It is finding a practical way to handle a short gap without turning the whole household into a stressful conversation. Lenme: Borrow and Lending approaches that problem as a finance app for quick cash advances, personal loans, and lending opportunities. I found it most interesting when viewed through a household lens: one person may need help, another may be comparing options, and everyone needs to understand exactly who is using the account and why.
The app is free to install and is developed by Lenme: Borrow and Lend. It has built a sizeable audience, with over 500 thousand installs, and its average score sits at 4.2 from around 22 thousand ratings. Those numbers suggest that it is not an obscure experiment, but they do not remove the need for careful judgment. Borrowing money through a mobile app is still a financial decision, not just a convenient tap-through task.
How Lenme fits into a shared household money problem
A realistic example is a household where one adult has an unexpected bill before payday. The other adult may not need to borrow personally, but may want to help compare the available route, check repayment details, or understand whether the request makes sense for the budget. Lenme can be useful in that situation because it puts borrowing and lending opportunities in one finance-focused environment rather than leaving the family to search through unrelated websites and messages.
I would still keep the actual account with the person whose finances are involved. A shared phone does not need to become a shared financial identity. If one partner opens the app to help another, the safest workflow is to discuss the purpose first, let the borrower enter their own information, and review the terms together without casually switching between personal accounts. That simple boundary matters more here than it would in a recipe or entertainment app.
The app’s central appeal is speed and concentration. Instead of treating a short-term cash need as a long research project, it gives the user a place to explore quick advances and personal-loan possibilities. That can be valuable when the alternative is missing a payment or relying on an informal arrangement that nobody documents properly. At the same time, speed can encourage rushed decisions, so I would use Lenme as a comparison and decision tool, not as permission to borrow automatically.
My main advice is to decide the repayment amount before accepting anything. Start with the household budget, not with the amount the app appears to make available. If the proposed repayment would force another bill onto a credit card or leave no room for food, transport, or utilities, the convenience is probably not worth it.
What the first setup means for a household
Lenme is rated for Everyone, but that label should not be confused with a recommendation for every member of a family. A finance app can be available to a broad audience while borrowing itself remains an adult responsibility. I would not hand a child a family member’s unlocked phone and assume that the age label makes financial access appropriate. The adult who owns the financial situation should control the account and the final decision.
On a shared device, I would begin by choosing one primary user and keeping that person’s session separate from anyone else’s. The most important setup question is not how quickly the app opens; it is whether another household member could accidentally view, edit, or submit financial information. Use the device’s normal account protection, avoid leaving an active session unattended, and do not save personal details in a place where another user can casually reuse them.
This is also a good moment to agree on a household rule: browsing together is acceptable, but submitting a request should require the borrower’s clear approval. That rule prevents a well-meaning partner from changing an amount, selecting an option, or continuing a process without the person who will carry the obligation understanding it.
The current version is 26.6.1 and it requires Android 8.0 or later. That makes compatibility fairly approachable for people using an older Android phone, although the experience can still depend on the device, operating system condition, and the quality of the connection. If the household shares one older phone, I would avoid doing a time-sensitive financial task when the device is nearly full, unstable, or needed by someone else.
Keeping the borrower, helper, and lender roles clear
One of the less obvious challenges with a lending marketplace is that “helping” can mean several different things. A partner may be helping with reading, a relative may be considering lending, and the person requesting money may be responsible for repayment. Those roles should never be blended simply because everyone is using the same screen.
I found it useful to treat the app as a coordination point rather than a family wallet. The borrower should know what they are requesting and why. A potential lender should decide independently whether the opportunity fits their own risk tolerance. A household helper can ask questions and check arithmetic, but should not make the financial decision for another adult.
This separation is especially important when a family member wants to lend money. Personal relationships can make a loan feel safer than it really is. Before proceeding, discuss the amount, expected repayment, and what happens if the borrower cannot pay on time. Lenme may make the opportunity easier to organize, but it cannot replace an honest conversation about the relationship and the risk.
Another practical tip is to keep a short written record outside the app of the household’s decision: why the money is needed, how repayment fits the budget, and who is responsible. I am not suggesting that the app lacks records; this is simply a useful household habit. It prevents later confusion when one person remembers the requested amount and another remembers the amount that was actually accepted.
Reading the opportunity instead of chasing the fastest answer
The store positioning emphasizes quick cash advances, easy personal loans, and AI-powered lending opportunities. In practice, I would approach the word “easy” cautiously. A smooth interface can simplify navigation, but it does not make the underlying financial commitment simple. The important work is still comparing the full cost, timing, repayment expectations, and consequences of choosing one route over another.
When reviewing an option, I would look beyond the amount that solves today’s problem. Ask how the repayment interacts with the next pay cycle, whether the household has a backup plan, and whether the borrowing need is genuinely temporary. A late utility bill and a recurring monthly shortfall are different problems. The former may be manageable with a carefully planned short-term solution; the latter usually calls for a budget change, creditor discussion, or longer-term support rather than repeated advances.
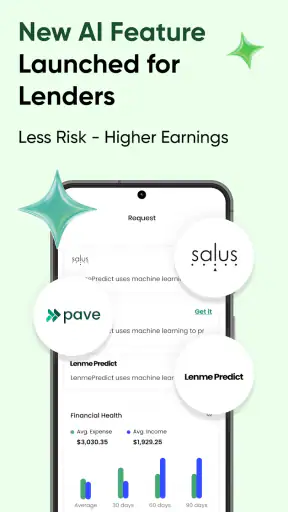
The AI element may make lending opportunities feel more tailored, but I would not treat an automated suggestion as personal financial advice. A recommendation can organize possibilities; it cannot know every household obligation, emotional pressure, or informal commitment. I prefer using such guidance as a starting point, then checking the real numbers myself.
This is where Lenme compares favorably with asking friends for money through text messages. A dedicated finance app can create a clearer process and reduce the awkwardness of explaining the same need repeatedly. It may also be more convenient than visiting a traditional lender for a small, urgent requirement. The trade-off is that a conventional bank or credit union may be a better choice for someone who wants an established long-term relationship, broader financial products, or in-person guidance.
Who should use it, and who should pause
I see Lenme as a reasonable option for an adult who has a specific, short-lived cash gap and is willing to read every condition before moving forward. It may also suit someone evaluating whether lending an amount to another person is appropriate, provided they understand that convenience does not eliminate risk. The free entry point makes it easy to explore, but exploration should not become repeated borrowing simply because the app is always available.
I would be more cautious if the household already depends on one advance to repay another. That pattern can turn a temporary fix into a cycle. I would also pause if the borrower cannot explain the repayment plan in plain language, if the request is being made under pressure from another person, or if a teenager is trying to use an adult’s device or account. In those cases, the right next step is a conversation and a budget review, not a faster application.
People who prefer predictable, traditional borrowing may be better served by comparing their bank, credit union, or another established financial provider first. Lenme is built around opportunities and speed, which can be useful, but some users will value a familiar institution’s existing support more than a marketplace-style experience. The best choice depends on whether the priority is quick exploration or a longer-term relationship with a provider.
There is also a cost consideration. Although the app itself is free, it includes in-app purchases ranging from $1.99 to $399.99 per item. I would not assume that installing the app tells me the complete cost of borrowing or lending. Before confirming anything, inspect the relevant terms and distinguish app access from the financial cost of a specific transaction. That distinction is easy to overlook when a free download is paired with an urgent money problem.
Age, trust, and the reality of shared devices
The Everyone content rating is helpful for general availability, but financial trust still needs an adult boundary. A child might use a shared phone for ordinary apps, yet that does not mean they should browse a borrowing service unsupervised. The risk is not only accidental action; it is also exposure to sensitive financial information that belongs to a parent, guardian, or another adult.
For couples or housemates, trust should not mean unrestricted access. If the phone belongs to one person but the money belongs to another, let the financially responsible person handle the account. If both adults are involved, decide in advance who may review opportunities, who may communicate with a potential lender, and who makes the final call. These small agreements reduce the chance that a shared device creates an unclear chain of responsibility.
I would also avoid using Lenme as a casual family teaching tool unless the lesson is about caution rather than borrowing. A young person can learn how repayment works through a household budget without being given access to real financial requests. The app’s broad age rating does not remove the need for supervision, context, and clear limits.
For privacy and trust, the best habit is simple: do not leave the app open when handing the phone to someone else. Review notifications and device previews as well, because financial messages appearing on a lock screen can reveal more than intended. These are ordinary phone habits, but they matter more when the app is connected to personal borrowing or lending decisions.
My household verdict after using the app
Lenme: Borrowing and Lending is most convincing when it is used deliberately: one adult identifies a defined cash gap, the household checks whether repayment is realistic, and everyone keeps their account and role boundaries clear. Its finance focus, free installation, and emphasis on quick advances and personal-loan opportunities make it easy to understand why it has attracted a substantial audience. The 4.2 average from roughly 22 thousand ratings gives it a credible starting point, while the developer, Lenme: Borrow and Lend, continues to present it as a focused borrowing and lending service rather than a general budgeting app.
My reservation is not about the idea of using a phone to explore financial options. It is about the temptation to mistake a fast process for a safe decision. The app can help organize a short-term choice, but it cannot decide whether borrowing is wise for your household, whether a friend should lend, or whether the same problem will appear again next month. Those judgments remain personal and financial, not technical.
If I were recommending it to a friend, I would say: use it when the need is specific, the repayment plan is already visible in your budget, and the account belongs to the adult making the decision. Keep children and casual device users away from active financial sessions, separate browsing from approval, and compare the complete terms with alternatives such as a bank, credit union, or direct bill arrangement. With those boundaries, Lenme can be a useful place to investigate a short-term solution. Without them, its convenience may encourage a decision that the household has not really had time to understand.
FAQ
What is Lenme: Borrowing and Lending, and how does it work?
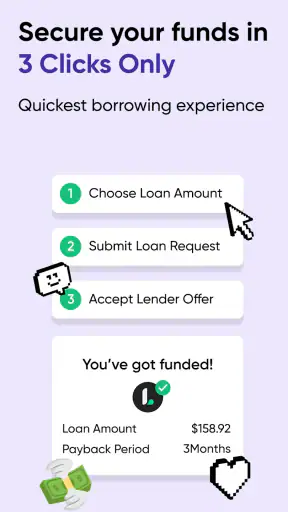
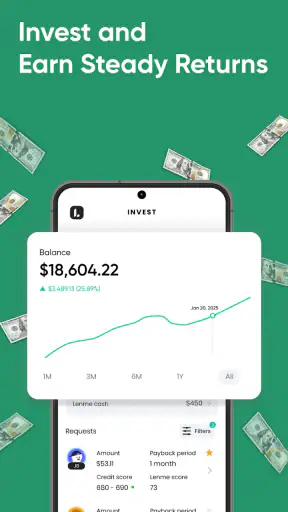
Lenme is a peer-to-peer lending marketplace that connects people looking to borrow money with individuals willing to lend. After creating an account, borrowers can submit a loan request with details such as the amount, purpose, and repayment terms. Lenders can review available requests and choose whether to fund them. Approval, funding, and repayment depend on the platform’s processes and the users involved.
Can anyone borrow money through Lenme?
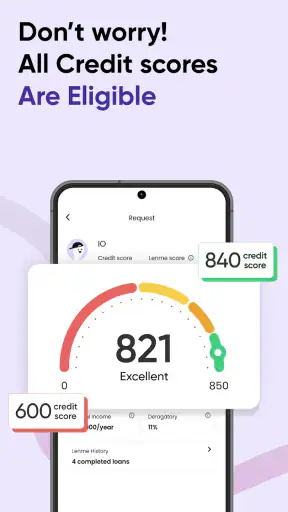
Not necessarily. Borrowers generally need to meet Lenme’s eligibility requirements, which may include being of legal age, living in a supported location, verifying their identity, and providing financial or personal information. A submitted request is not a guarantee of approval or funding. Availability can also vary according to creditworthiness, lender interest, loan amount, and the rules applicable in the user’s region.
Is Lenme safe to use for borrowing or lending money?
Lenme may provide tools for identity verification, loan management, and communication, but users should still understand the risks of peer-to-peer lending. Lending money is not the same as holding a guaranteed deposit, and repayment may be delayed or missed. Before using the app, review its privacy policy, fees, lending terms, dispute procedures, and any protections available in your location.
What fees or costs should users expect on Lenme?
The total cost can depend on the type of transaction, the requested loan, the repayment schedule, and the fees charged to borrowers or lenders. Some costs may be shown during registration, loan-request creation, funding, or repayment. It is important to read the final terms carefully before accepting an offer, since late payments, service charges, or other applicable costs may affect the overall amount.
What information does Lenme require, and how is it used?
To operate a lending marketplace, Lenme may request information such as your name, contact details, identification documents, financial information, and repayment-related data. This information can be used to verify accounts, evaluate requests, prevent fraud, facilitate transactions, and meet legal requirements. Before submitting sensitive details, check the app’s current privacy policy and confirm what data is collected, shared, and retained.


